Import from China to Nigeria in 2026: Duties, Documents and Landed Cost
Published by Aeonix Trade.
Last fact-checked: 9 November 2026.
A Lagos hardware buyer ships one LCL lot of door fittings, handed over FCA at the Ningbo container terminal, for clearance at Lagos. The factory calls the price FOB. For cartons handed to the carrier before the ship is loaded, ICC recommends FCA rather than FOB. Write "FCA Ningbo container terminal."
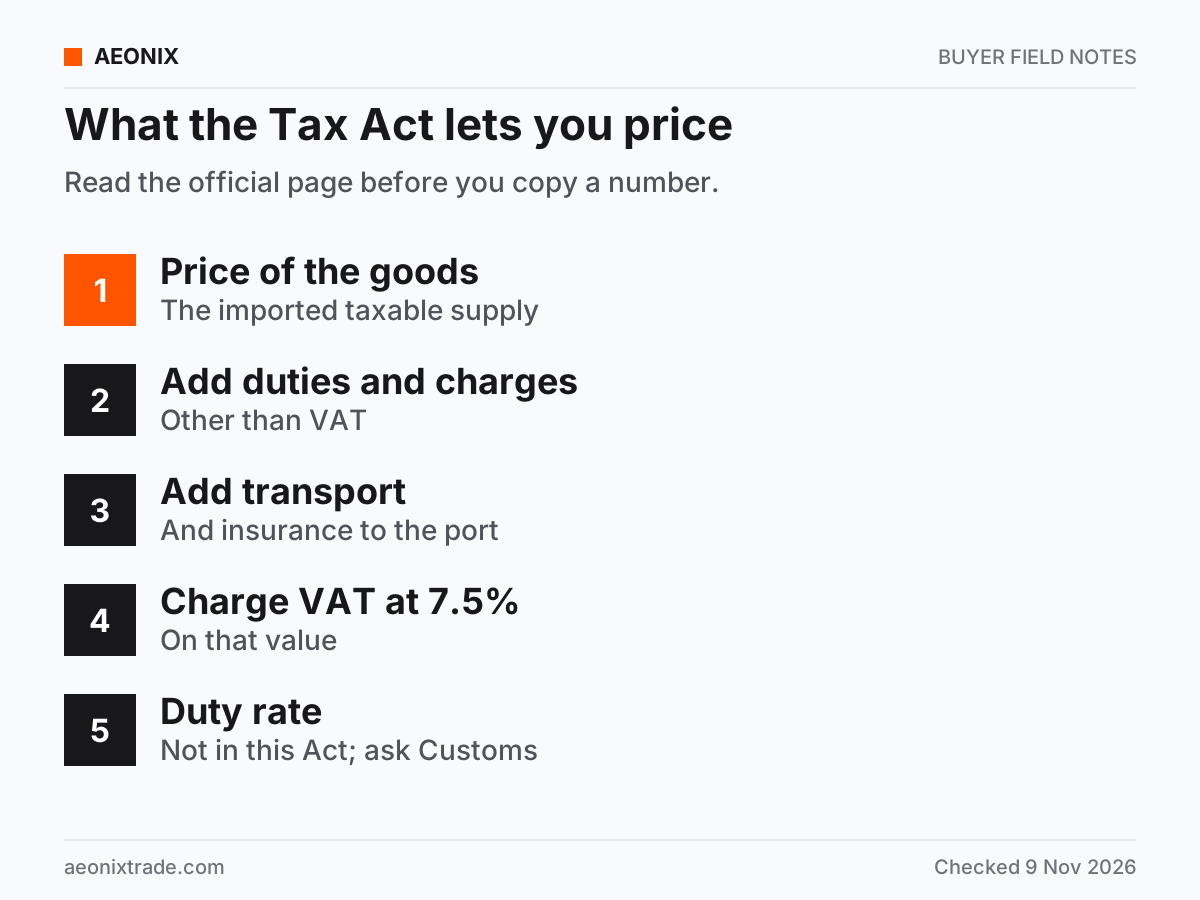
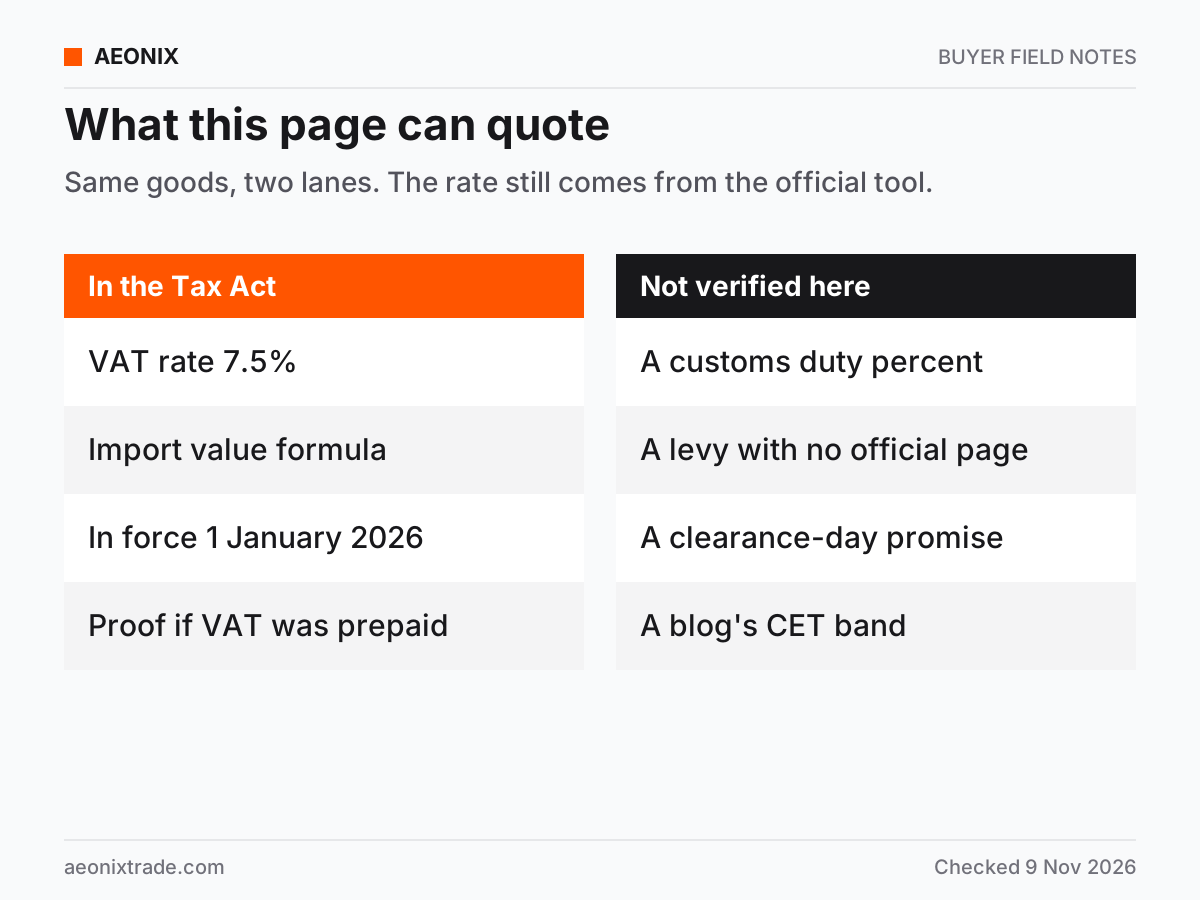
To import from China to Nigeria, the tax side has a rate the statute prints. Importing from China to Nigeria still needs the duty looked up separately. The Nigeria Tax Act 2025, section 147, charges VAT on the value of all taxable supplies at 7.5%. The Act's commencement line is 1 January 2026. Section 149 says the value of an imported taxable supply is the price of that supply, plus taxes, duties and other charges levied outside Nigeria or because of the importation, other than the VAT itself, plus the costs of commission, transport and insurance up to the port or place of entry. The gazette copy is the National Assembly text at Nigeria Tax Act 2025, read on 9 November 2026.
A typical Lagos lot
Door fittings in commercial quantity are not a gift parcel. The VAT base is not the FCA unit price alone. Section 149 adds the duties and the other charges, and it adds transport and insurance to the Nigerian port. If the freight invoice is missing, the VAT value is incomplete, and the assessment will not match the spreadsheet you used to accept the MOQ. Put freight and insurance on their own lines. Customs value in the wider sense follows the WCO valuation rules. The VAT value for this shipment is the formula in section 149. Do not mix the two and then call the result "CIF plus 7.5%" without the duties the section adds.
Section 150(8) says that where taxable goods are imported through an online platform operated by a non-resident, and VAT has already been collected by the Service or by a person the Service appointed, the goods are not charged VAT again at clearance if you can prove the payment. A trade lot of fittings bought from a factory, under your own contract, is not that platform case. Expect VAT on the section 149 value unless an exemption you can point to in the Act says otherwise. This page does not invent an exemption for hardware.
Duty stays on the customs tariff
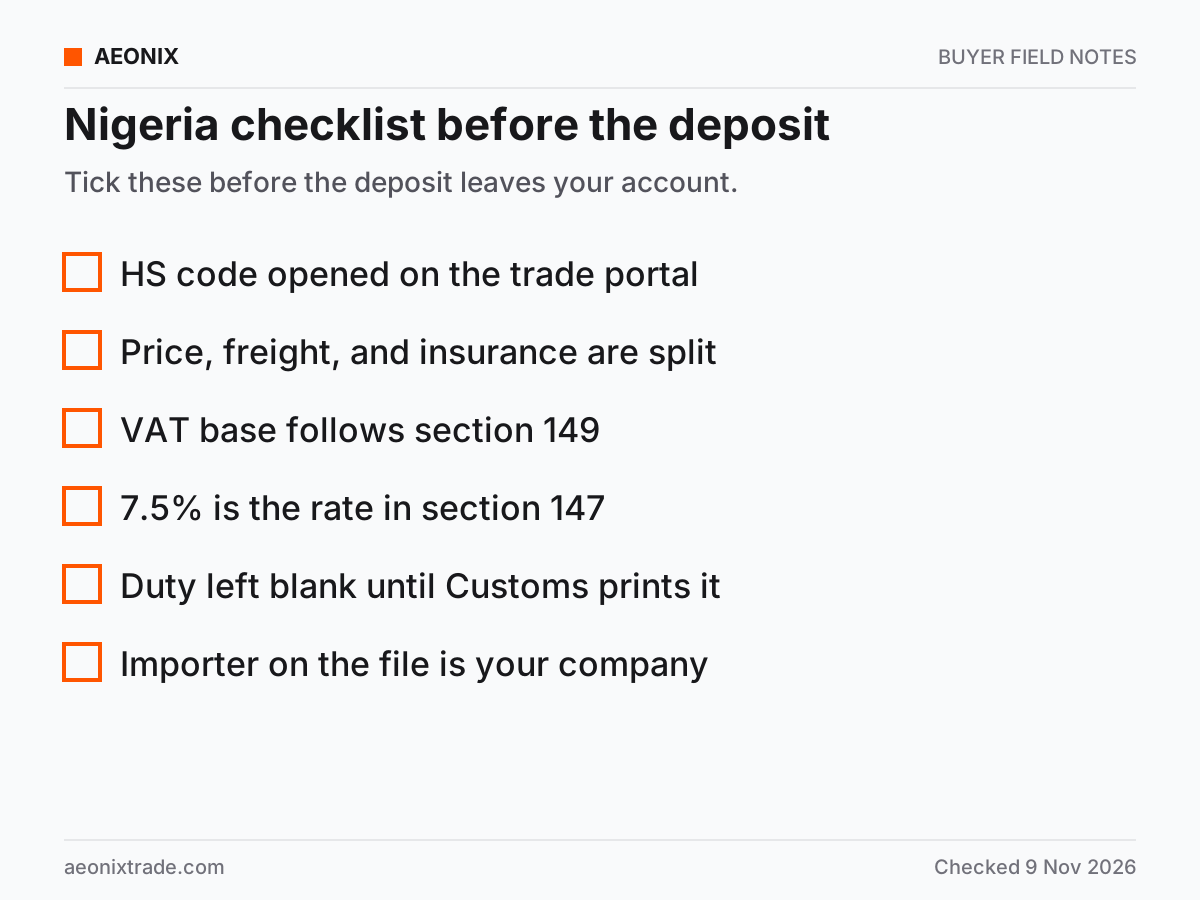
Nigeria import duty is a tariff question. On 9 November 2026 the Nigeria Customs Service website did not return a page that could be read from here, so no duty percent, no levy percent, and no form number from that site is repeated. Use the Federal Ministry of Industry, Trade and Investment trade portal, which did open. It is the official portal for looking up a product by keyword and HS code on the import side. The page is Nigeria Trade Portal, and the procedure list it points to is procedures. Open the fittings there with your broker before you wire the deposit. If the portal's procedure for that HS code asks for a permit or a standards document, that document is part of the order, not a surprise at Lagos.
A DDP offer that names a Chinese forwarder as the importer does not remove section 149. It only hides who will be asked for the money. If your company will sell the fittings, your company should be the name on the clearance and should hold the assessment.
Landed cost before the deposit
Use the landed-cost sheet. Leave the duty cell blank until the broker reads the live customs tariff. Fill VAT only from section 147 and section 149.
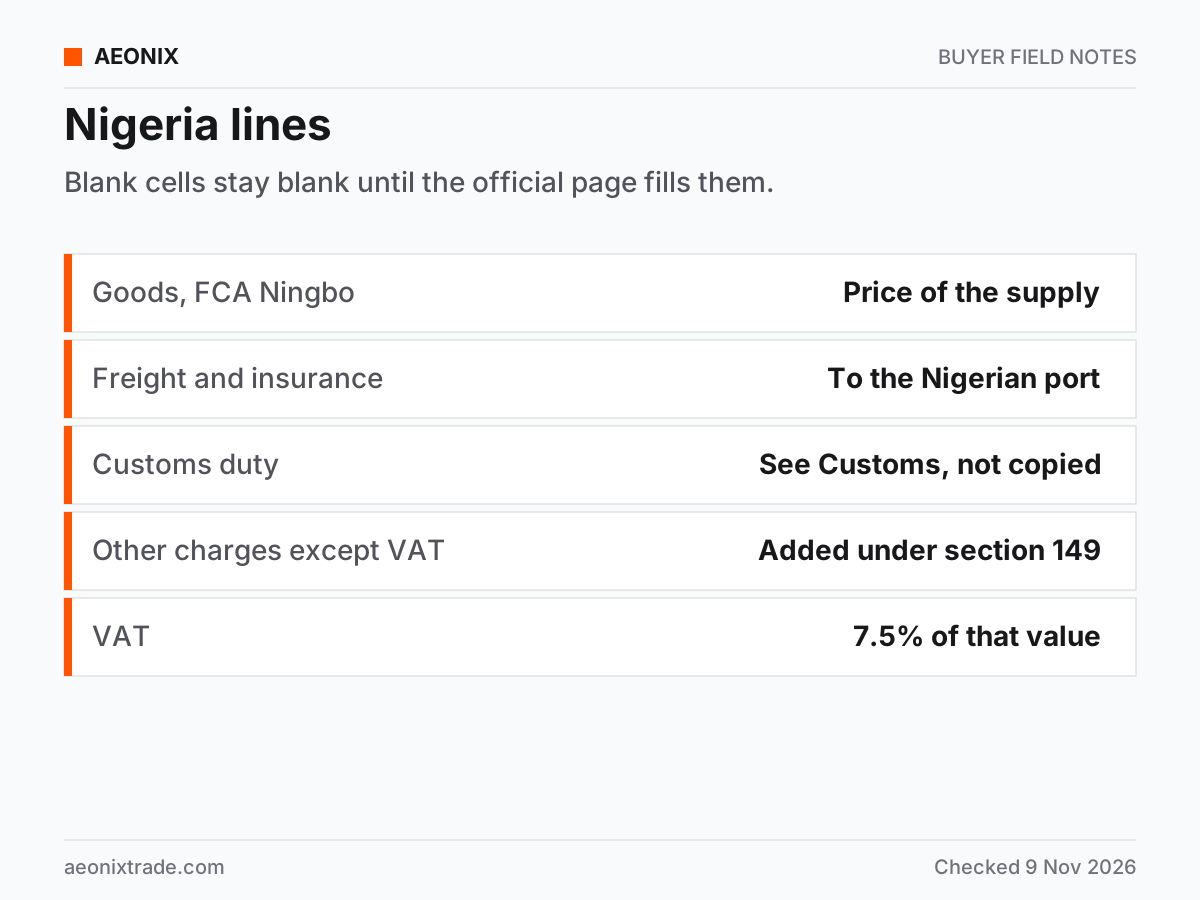
| Line | Ask for this | Do not assume |
|---|---|---|
| Goods, FCA Ningbo | The price of the supply, and the specification | That FCA includes freight to Lagos |
| Transport and insurance to the port | Invoices, because section 149 adds them | That VAT is charged on the factory price alone |
| Duties and other charges, except VAT | The broker's reading of the live tariff | A percent copied from a blog |
| VAT | 7.5% of the section 149 value, as of the Act in force 1 January 2026 | That a platform rule removes VAT on a factory contract |
| Product procedure | The trade-portal page for this HS code | That hardware needs no permit because it is "general goods" |
| Who clears | Your company, or a named importer who will show you the assessment | That the forwarder is the importer because the quote said delivered |
Where this lane goes wrong
- Building a resale price with a duty percent that no customs page in front of you actually prints.
- Forgetting freight and insurance in the VAT value, then arguing with the assessment.
- Treating a factory contract as if an online platform had already collected the 7.5%.
- Shipping before the trade-portal procedure for the HS code has been opened.
- Paying the TT to an account that does not match the seller. The supplier check comes first.
The wider file is the first-time compliance checklist. After the ship berths, use the arrival sequence. How the shared container is built is the LCL service and the LCL walkthrough. Pakistan's 18% sales tax is a different statute: the Pakistan guide. The UK duty lookup is different again: the United Kingdom guide. The hub is import from China.
Questions buyers ask
Can I start with LCL?
Yes. LCL does not change section 147 or section 149. The price, the duties, and the freight to the port still build the VAT value.
What is the duty from China?
Not stated here. The customs site did not return a readable tariff on 9 November 2026. Open the trade portal for the HS code and have the broker read the live customs tariff before you treat any percent as real.
Who pays the 7.5%?
The importer, on the value section 149 describes, unless you are in the narrow case where VAT was already collected on a non-resident platform and you can prove it. A factory contract FCA Ningbo is the first case, not the second.
See also Import from China to Kenya in 2026, which Incoterm to use, and the customs clearance sequence.
Official sources
- Nigeria Tax Act 2025: section 147, VAT at 7.5%, commencement 1 January 2026. Section 149, value of an imported taxable supply. Section 150(8), no second VAT charge where a platform collection is proved. Read 9 November 2026.
- Nigeria Trade Portal, Federal Ministry of Industry, Trade and Investment: product and HS lookup for import procedures.
- Trade portal procedures, linked from the ministry portal.
- WCO customs valuation.
- Incoterms 2020.
The Nigeria Customs Service site was not usable on the check date. Duty bands, surcharge names, and form numbers from unofficial pages are left out on purpose.
If you want the Ningbo handover checked before the deposit, use the RFQ form.
Submit sourcing request
Can't find what you need?
Start with a product or image link, an approximate quantity and destination. Other details can follow.